SMEDAN's New
N500m Interest-Free Fund: How Nigerian Small Business Owners Can Access It
If you run a small business in Nigeria, you already know that access to
affordable capital is the single biggest obstacle standing between you and
growth. Commercial bank loans come with interest rates that can cripple a small
operation before it even gets off the ground, and many entrepreneurs simply
have no collateral to offer. This week, the Small and Medium Enterprises
Development Agency of Nigeria (SMEDAN) announced a new initiative aimed
squarely at that problem — and it is structured in a way that is genuinely
different from anything the agency has tried before.
What Exactly Is the Grow Fund?
The Small and Medium Enterprises Development Agency of Nigeria has unveiled the
Grow Fund for Small Businesses in Nigeria, a ₦500 million zero-interest
revolving fund for Micro, Small and Medium Enterprises across the country.
SMEDAN Director-General Charles Odii announced the initiative in Abuja as part
of activities marking the 2026 World MSME Day, with a clear message: access to
affordable finance remains one of the biggest obstacles facing Nigerian MSMEs,
and this fund is a direct response to that reality.
What sets this fund apart from previous government interventions is not just
the zero-interest structure — Nigeria has had interest-free schemes before —
but the distribution model. SMEDAN is not giving the money directly to
individual entrepreneurs. Instead, the funds will be disbursed through
cooperatives, trade unions, business membership organisations, and recognised
associations.
"We are not giving the money to individuals directly," Odii
explained. "We are giving it to associations that understand their members
and can manage the funds responsibly." According to him, this
association-based lending model is designed to improve accountability,
strengthen loan recovery, and ensure the funds genuinely reach hardworking
business owners rather than being diverted or defaulted on without
consequence.
Why the Association Model Matters for You
If you are a small business owner wondering how this affects you practically,
here is the key takeaway: your path to this fund runs through your trade
association, cooperative society, or business membership group — not through a
direct individual application to SMEDAN.
This is actually a significant structural shift, and it carries real
implications. Unlike conventional commercial bank loans, which are subject to
the banking sector's Global Standing Instruction (GSI) framework that can
freeze a defaulter's accounts across the entire banking system, this new
financing arrangement channels credit through recognised associations and
cooperatives that will assess beneficiaries themselves, manage disbursement,
monitor how the funds are utilised, and take responsibility for ensuring
repayment.
In practical terms, this means three things for Nigerian entrepreneurs. First,
if you are not currently a member of a registered trade association, market
union, or cooperative society relevant to your business sector, now is the time
to join one. Second, your association's internal governance and credibility
with SMEDAN will likely determine how quickly and how much funding your members
can access — so it is worth getting involved in how your association is run.
Third, repayment terms will be negotiated between SMEDAN and each participating
association individually, meaning the flexibility of your repayment schedule
may depend heavily on which group you belong to.
What the Money Can Be Used For
According to Odii, beneficiaries will be able to use the interest-free loans to
increase working capital, acquire business tools and equipment, and secure
workspaces needed to expand their operations. This is a broad mandate that
covers most of the practical needs small Nigerian businesses face — whether
that is a tailor needing new sewing machines, a food vendor needing cold
storage equipment, or a small trader needing capital to buy stock in bulk at
better wholesale prices.
Where the Programme Currently Stands
The initiative has already commenced in Lagos and Ogun states, according to
Odii, with SMEDAN's long-term objective being the establishment of broader
enterprise support infrastructure nationwide. The agency is also working to
expand the fund's reach beyond its initial ₦500 million through partnerships
with state governments, development partners, and other institutions willing to
provide matching funds — meaning the total pool of available financing could
grow considerably as more partners come on board.
SMEDAN has also disclosed that it secured a $12 million commitment from the
South Korean government to establish a world-class Skills Acquisition Centre in
Abuja, which will provide vocational and entrepreneurial training to thousands
of young Nigerians and improve the productive capacity of MSMEs nationwide. The
agency is awaiting land allocation from the Federal Capital Territory
Administration to begin construction.
A Bigger Policy Shift Is Coming
The Grow Fund is not happening in isolation. Odii revealed that SMEDAN is
currently reviewing a draft National MSME Policy that will soon be forwarded to
President Bola Tinubu for approval. The proposed reforms within that policy are
ambitious and, if implemented, could reshape the operating environment for
small businesses considerably. They include single-digit interest loans for
MSMEs as a standard offering, reserving 30 percent of government procurement
contracts specifically for small businesses, and removing age limits from government
intervention programmes — a change that would open up funding access to older
entrepreneurs who have historically been excluded from many youth-focused
schemes.
SMEDAN also said it would engage relevant regulators on concerns affecting
small businesses, including burdensome advertising registration requirements
that many entrepreneurs have flagged as an unnecessary barrier to growth.
Why This Matters Right Now
Odii connected the urgency of this push to a specific upcoming opportunity:
Nigeria is preparing to host a major international cultural event in Lagos next
year, and many local businesses will need financing and capacity support to
meet the expected surge in demand. He pointed to Algeria as an example, noting
that when Nigerian officials visited the country, they observed how the
Algerian government had already provided funding to small businesses ahead of
time, enabling them to scale up production before international visitors
arrived. "Nigeria should not be different," Odii said.
The Collateral Problem This Model Is Trying to Solve
To understand why SMEDAN has deliberately moved away from individual lending,
it helps to understand exactly what has historically gone wrong with small
business financing in Nigeria. Commercial banks typically require collateral —
landed property, fixed deposits, or guarantor arrangements — that the vast
majority of micro and small business owners simply do not have. A market trader
selling tomatoes, a tailor running a one-room shop, or a young graphic designer
working from a rented apartment has no asset base that a commercial bank would
accept as security for a loan, regardless of how viable or profitable their
actual business might be.
Previous government-backed interventions that bypassed this collateral
requirement often ran into a different problem: weak monitoring and poor
recovery rates, which made the schemes financially unsustainable and eroded
political will to expand them. Nigeria's history is littered with
well-intentioned interest-free or low-interest loan schemes that collapsed
within a few years because there was no effective mechanism for ensuring funds
were used as intended or repaid on schedule once disbursed to individuals
scattered across the country.
The association-based model SMEDAN is now deploying attempts to solve both
problems simultaneously. By channeling funds through trade unions,
cooperatives, and business membership organisations that already have
established relationships with their members, SMEDAN is effectively outsourcing
the due diligence, monitoring, and recovery functions to groups that have far
better visibility into which of their members are genuine, creditworthy
entrepreneurs versus opportunistic applicants. A market traders' association,
for instance, knows exactly which of its members actually run viable stalls,
how long they have been trading, and whether they have a track record of
meeting financial obligations to the group — information no bank loan officer
reviewing a stack of paper applications could realistically verify.
Lessons From Similar Models Elsewhere
This is not an entirely novel approach globally. Group lending and
cooperative-based microfinance models, most famously associated with
Bangladesh's Grameen Bank, have demonstrated for decades that peer
accountability within tightly knit groups can produce dramatically higher
repayment rates than individual unsecured lending, even among extremely
low-income borrowers with no formal collateral. The logic is straightforward:
when an entire association's future access to funding depends on its members
honouring their repayment obligations, social pressure and mutual
accountability within the group become a powerful substitute for traditional
collateral.
Whether Nigerian trade associations and cooperatives can replicate this
discipline at scale remains to be tested, which is presumably why SMEDAN has
chosen to pilot the Grow Fund in just two states, Lagos and Ogun, before
committing to a full national rollout. Both states have relatively
well-organised commercial and trading sectors, with established market unions
and business associations that have operated for years, making them sensible
testing grounds for a model that depends heavily on the underlying strength and
discipline of the participating groups.
The Bottom Line for Nigerian Entrepreneurs
For business owners across Nigeria, particularly those running market stalls,
small manufacturing operations, food businesses, fashion enterprises, and
service-based ventures, the practical action item is clear: connect with your
relevant trade association or cooperative society now. Find out whether your
group is engaging with SMEDAN or planning to. If no such association exists in
your sector or locality, consider whether organising one with fellow business
owners could position your community to access this and future government
financing.
The Grow Fund represents a meaningful, if modest, step toward solving Nigeria's
persistent small business financing gap. ₦500 million is not a vast sum when
spread across millions of MSMEs nationwide, but as a pilot for a fundamentally
different lending model — one built on community accountability rather than
individual collateral, and informed by approaches that have worked in other
developing economies — it could become the template for much larger
interventions if it proves successful in Lagos and Ogun before its planned
national expansion. For now, the smartest move any small business owner in
Nigeria can make is to stop waiting for an individual loan application process
that may never come, and instead invest time in building or strengthening the
collective business networks that SMEDAN has signalled will be the gateway to
this and future funding.
SMEDAN's New N500m Interest-Free Fund: How Nigerian Small Business Owners Can Access It
By NaijaToday Desk · 30 June 2026 · 6 min · 👁 6
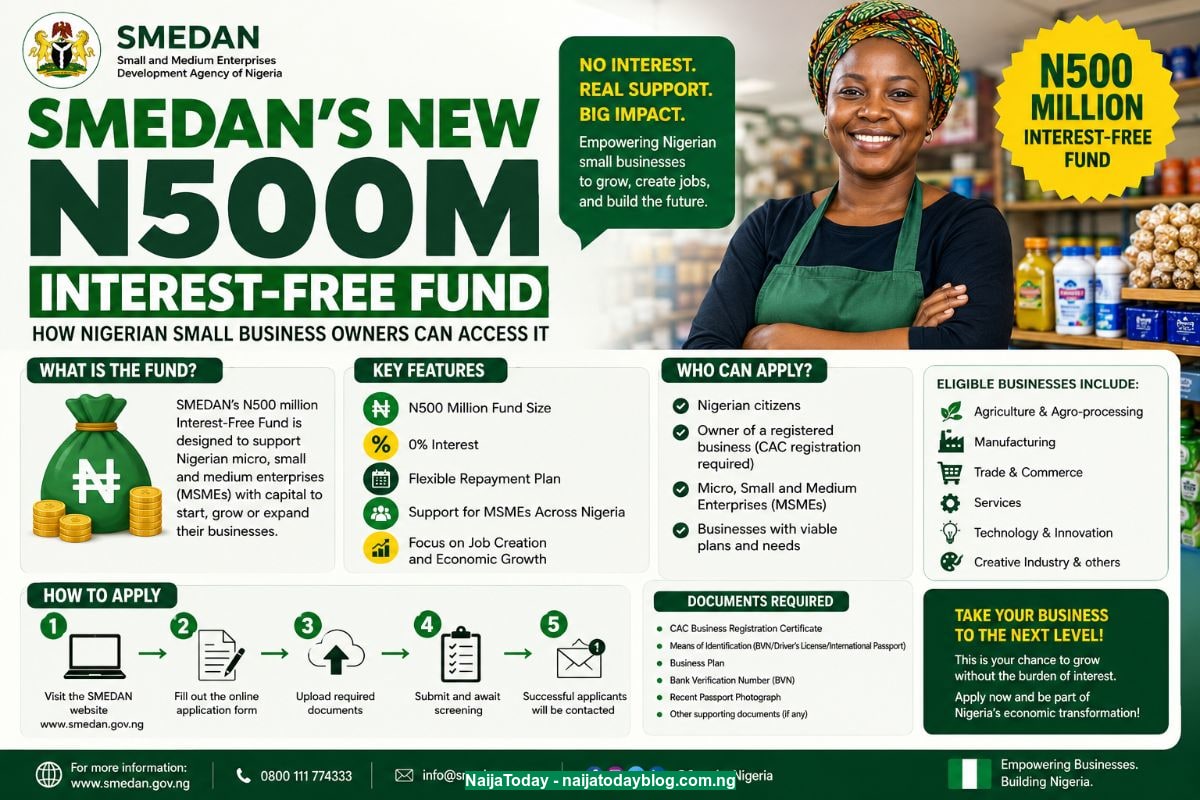
SMEDAN just launched a N500 million zero-interest "Grow Fund" for Nigerian small businesses — but you can't apply as an individual. Here's exactly how the new association-based model works and how to position your business to benefit.
#smedan grow fund#zero interest loan nigeria#small business loan nigeria 2026#msme funding nigeria#charles odii smedan#business funding nigeria#cooperative loan nigeria#world msme day 2026
How does this story make you feel?
No account or sign-in needed. You can react instantly.
Share:
NaijaToday Desk
The NaijaToday newsroom
More Stories to Explore
More reporting selected from NaijaToday, based on topics and categories.